ICE Partners with Hyperliquid, Traditional Exchanges' Moat is Shifting

 Prefer us on Google



The matching engine is not the moat; the regulatory license is.
Written by: Vaidik Mandloi
Compiled by: Luffy, Foresight News
Everyone is currently discussing the token price of Hyperliquid, and this collaboration between ICE and Hyperliquid is being referred to as one of the heaviest institutional endorsements in the history of the crypto industry. But there is a question: since electronic trading replaced floor trading, the matching engine and clearing settlement have always been the technical foundation for traditional exchanges. Why is ICE choosing to actively give this up? (Note: The exchanges mentioned in this article mostly refer to traditional futures and securities exchanges, such as NASDAQ and NYSE.)
For decades, exchanges have been promoting to shareholders that the matching engine is their moat. But if this capability can be outsourced to a protocol that has only been around for two years, what core value is left for the exchanges?
I believe that the business model of exchanges is about to undergo a disruptive change, and this collaboration is the starting point for that transformation.
What is Left for Exchanges?
In the early 21st century, when electronic trading eliminated floor trading, everyone thought that floor market makers were the victims. Those traders in colorful vests waving documents in the NYSE hall, completing trades with gestures and eye contact, were replaced by servers in New Jersey data centers. Financial media at the time lamented the end of this ceremonial era.
But few pointed out a fact: the New York Stock Exchange itself was not impacted at all. That exchange building was later converted into a studio; the listing business continued to generate profits, even higher than before. The regulatory qualification that allows companies to list on the NYSE retained its value before and after the arrival of electronic trading.
Floor market makers mistakenly believed they were the exchange itself. In reality, they were merely the technical layer of the exchange. When better technology emerges, exchanges can easily replace them.
When I read the news about the collaboration between ICE and Hyperliquid, I kept reflecting on this history. In my view, the same plot is being replayed, just at a higher level. For the past 25 years, CEOs of major exchanges have been telling shareholders: the matching engine is the new generation of trading floor. This self-developed software used to match buy and sell orders determines the quality of the exchange, spending billions to build hosting facilities and pursuing microsecond latency is a competitive advantage that others cannot replicate.
However, the real moat has always been hidden beneath all the technology, in an extremely inconspicuous place: in the filing cabinets of the Commodity Futures Trading Commission (CFTC) ------ that is, regulatory qualifications.
For example: a pension fund wants to trade crude oil futures. The fund manager will not look for the exchange with the best matching engine. They will contact brokers from Goldman Sachs or JPMorgan, and the brokers have clearing agreements with the CME (Chicago Mercantile Exchange). The CME holds a derivatives clearing license issued by the U.S. government, and obtaining this license requires decades of continuous capital investment and gradual accumulation of regulatory trust.
If a counterparty defaults, the CME's guarantee fund bears the loss first; if the guarantee fund is insufficient, CME must use its own funds to cover the shortfall. The entire system operates based on a regulated guarantee chain. This system cannot be quickly replicated by anyone; to obtain it, one must spend over a decade proving to federal regulators that they are worthy of holding institutional funds. Meanwhile, the matching engine and trading software are the least significant links in the entire chain. A reliable engineering team can write them in a few months. What they cannot create is regulatory trust.
The classic case of McDonald's can be compared to the changes happening in the exchange industry today. In 1957, McDonald's first CEO Harry Sonneborn told a group of MBA students that everyone misunderstood the company's main business. The students thought McDonald's sold hamburgers, but he denied this: McDonald's is in the real estate business.
McDonald's does not need to grill hamburgers to make money. Franchisees are responsible for making hamburgers, while McDonald's owns the land beneath the stores. Regardless of how tasty the hamburgers are, the land will continue to appreciate. For seventy years, all of McDonald's strategic decisions have stemmed from this underlying understanding.
Jeff Sprecher (founder of ICE) has long seen through this logic; he may be the most underrated strategist in the U.S. financial circle. All his acquisitions throughout his career have followed the same thought process. In 2013, he spent $11 billion to acquire the NYSE, focusing on the market data business ------ today, all institutional trading teams in the U.S. pay millions of dollars annually for this market data; without it, they cannot trade.
From 2018 to 2023, he acquired two mortgage platforms, and now most residential mortgage processes in the U.S. are handled by them. At the time, analysts were puzzled as to why an exchange company would buy mortgage software. But his strategy has remained unchanged: acquiring toll booths that cannot be bypassed in the flow of capital.
And now, he has actively handed over the matching and settlement technology for perpetual contracts to Hyperliquid. Everyone is puzzled: why is ICE giving up its core cards? But Sprecher provides an answer with this costly action: the matching engine has always been just a “hamburger,” while regulatory qualifications are the land.
The CME is the best evidence. In 2004, Eurex opened an exchange in the U.S., trying to take CME's U.S. Treasury futures business with lower fees; in 2009, several Wall Street banks jointly launched the ELX exchange, making the same attempt. Both ultimately failed. The reason is simple: all traders' positions are at the CME clearinghouse, and new trades can offset existing positions, saving margin far more than the fee discounts offered by competitors.
Therefore, if the core value sold by exchanges is access qualifications rather than technology, and if ICE has already proven through action that the technical layer can be outsourced to a protocol that was established only two years ago, the next question naturally arises: why now? Why did Sprecher choose to break the norm at this time?
Because a type of product is impacting traditional exchanges, eroding their liquidity and moats: perpetual contracts. Perpetual contracts are the fastest-growing category in the history of derivatives, and their underlying design will directly hollow out the revenue model that traditional exchanges rely on to support their stock prices.
The real threat of perpetual contracts to traditional exchanges comes from roll-over income. Traditional futures contracts have expiration dates. Traders who want to hold positions long-term must switch to the next contract before expiration. Each roll-over allows the exchange to collect fees. In other words, holding a position for a whole year could generate six fees. It is this roll-over income that allows CME's price-to-earnings ratio to reach 30 times instead of 15 times. But perpetual contracts directly eliminate the need for roll-overs. They never expire, do not require contract switching or roll-overs; the funding rate is used to anchor spot prices, and funds are directly transferred between the trading parties, leaving the exchange with nothing. When perpetual contracts officially entered the U.S. regulatory discussion, the combined market value of major exchanges evaporated by about $18 billion in just two days.
Sprecher had no choice; he had to launch perpetual contracts. Last year, the global trading volume of perpetual contracts reached $90 trillion, and Hyperliquid achieved astonishing trading volume in its first complete fiscal year without any U.S. users; almost all institutional trading desks wanted to trade perpetual contracts.
However, launching perpetual contracts would also eat into the roll-over income of traditional futures ------ and this income is the foundation of his entire business. The options in front of him all have drawbacks; he can only choose a plan that causes slower harm to keep the licensing business alive.
He did not spend billions to build a continuous clearing system from scratch, nor did he spend years communicating with regulators to persuade the CFTC to recognize this new system; instead, he directly integrated with the underlying infrastructure that already natively supports perpetual contracts.
Another point to clarify: Hyperliquid itself is not an exchange; it is a protocol. The protocol does not care whether the business built on it is from the parent company of the NYSE or an anonymous team in Bali launching a MEME coin trading market. It only handles order matching and settlement.
Owning the NYSE, ICE has structurally become an application running on someone else's platform. Just like a startup builds its entire business on AWS cloud, Amazon provides computing power and does not care what business runs on top.
Using the “fat protocol” theory proposed by Joel Monegro in 2016, which has been widely discussed: ICE has actively transformed itself into an application running on a fat protocol. The protocol layer captures the value of the underlying infrastructure; what the application layer can earn is only the premium brought by compliance qualifications and institutional trust.
Sprecher bets that this trust premium is substantial enough to support a large business, and I agree with this judgment. However, the overall valuation of the exchange sector will face impacts that the market has not fully digested. If the matching and settlement technology that has supported high valuations for exchanges over the past fifteen years can be outsourced to a protocol that did not exist three years ago, what exactly was bought with those previous high valuations?
The previous valuations implied an assumption: exchanges held self-developed core technologies that others could not access. This time, ICE proved that technology is merely a replaceable module. What remains are regulatory licenses and distribution networks. These assets are indeed valuable, but they no longer belong to technology assets; they resemble utility assets more.
The Underlying Language of the Financial System
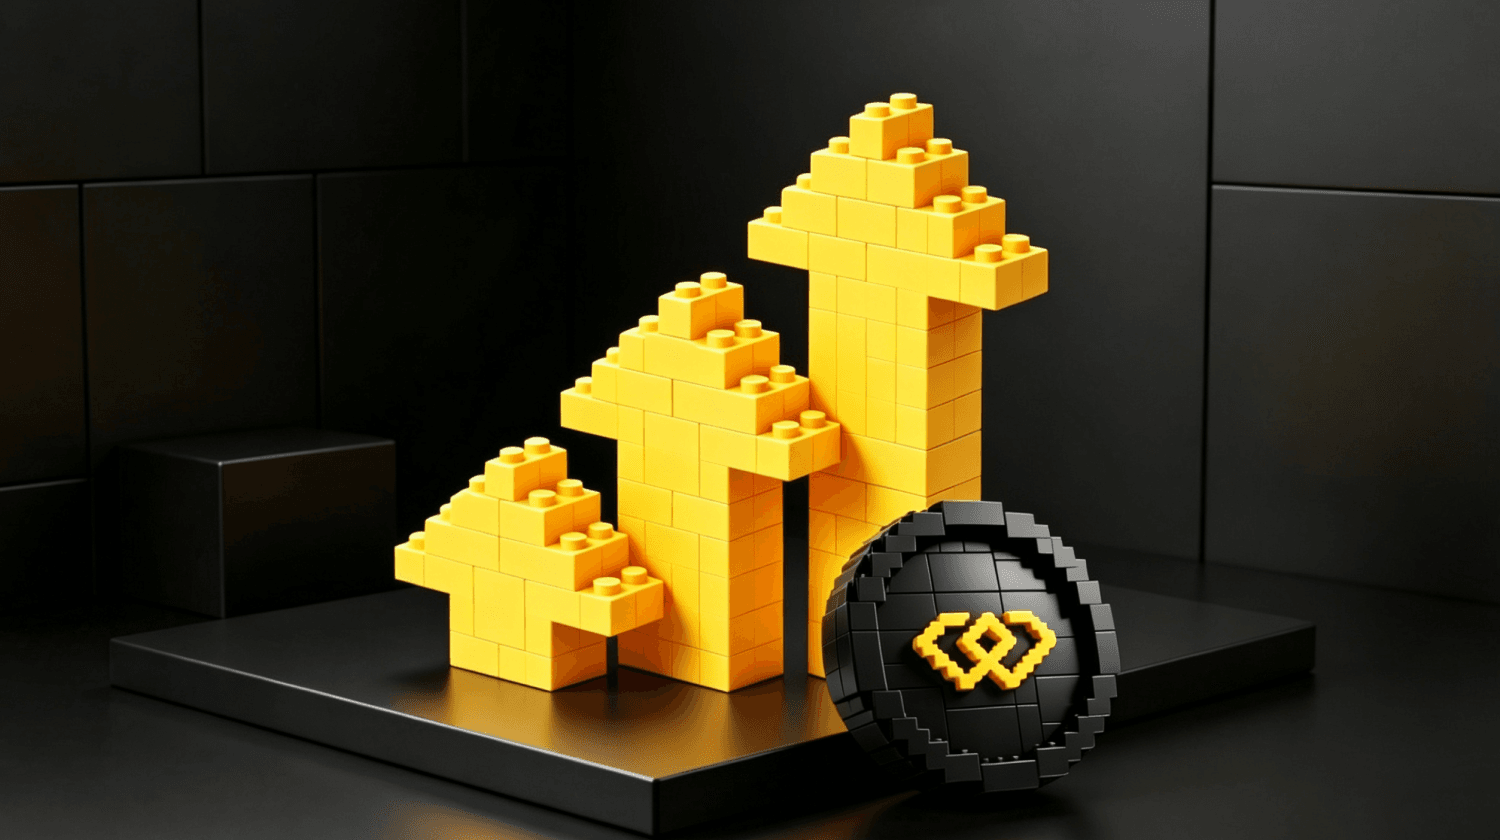
The vast majority of reports interpret the collaboration between ICE and Hyperliquid as ICE adding a new trading product, as if it were just adding another dish to the menu. But perpetual contracts are not a product; they are a set of financial primitives. You can think of them as Lego blocks. A single block may seem ordinary, but this foundational component is versatile enough to build almost anything when combined.
Perpetual contracts are similar. Stablecoins like DAI are essentially a type of perpetual contract, margin futures are perpetual contracts, and even Uniswap LP positions can be approximated as perpetual contracts. They may appear to be completely different financial products, but at their core, they share the same mathematical structure. As long as these foundational components are reasonably combined, options, structured products, insurance contracts, and any financial instrument can be reconstructed.
The mathematical principle behind this is the Taylor series. In simple terms, a settlement engine designed for perpetual contracts is not just used to trade a single product but can build a universal engine for all financial products. ICE did not just add a new item to its shelf; it integrated a set of underlying primitives that can accommodate all categories on the shelf in the future. Stock settlement can be understood as a first-order perpetual contract, stablecoin settlement is a zero-order perpetual contract, and options exposure is a combination of higher-order perpetual contracts; the mortgage platform under ICE also processes pledged loans, which are essentially variants of this set of primitives.
ICE has integrated a set of infrastructure; in the future, all such capital flows can operate through the same settlement layer. I even feel that Sprecher himself may not fully understand what he has integrated. This is not a criticism but a compliment to the Hyperliquid team ------ aside from a small circle of native crypto researchers, few have seriously deduced: if the mathematical logic behind perpetual contracts is fully implemented, what will it eventually evolve into?
CME is now the riskiest target in the exchange sector. Its monopoly foundation comes from the liquidity aggregation effect and regulatory licenses. The premise for the liquidity aggregation effect to hold is that there is no alternative trading channel that can achieve the same exposure at a better cost.
Perpetual contracts are that alternative channel. Traders holding perpetual positions do not have to pay any roll-over fees. When the cost of maintaining a position changes from six fees a year to zero, institutional trading teams will eventually migrate, regardless of how many years they have cleared at CME. This is akin to Kodak inventing the digital camera but spending twenty years continuing to promote film ------ because all its profits rely on the printing business. CME has the capability to self-develop a continuous clearing system and has channels to persuade the CFTC to approve it, but it cannot admit that everything it has built over the past forty years is merely a module that a crypto protocol has already natively implemented and can replace.
On the other hand, changes are also occurring from within the crypto industry. Kraken acquired NinjaTrader (which holds FCM broker licenses) and Bitnomial (which has obtained both CFTC-issued DCO clearinghouse and DCM trading platform qualifications). A native crypto company has already obtained the full set of regulatory qualifications that traditional exchanges rely on for self-preservation.
ICE's route is to outsource technology to crypto protocols, maintain regulatory licenses, and retreat to the application layer. Kraken's route is to acquire regulatory qualifications, retain native crypto technology, and penetrate the traditional financial sector.
Both routes are heading toward the same destination: regulated perpetual contracts running on continuous clearing infrastructure, distributed to institutional clients by licensed intermediaries. It is still difficult to determine which route can establish a more enduring moat.
If I were to bet: looking at a five-year horizon, Sprecher is likely correct; over a fifteen-year long cycle, he may miscalculate. The trust premium for institutions is indeed substantial, and native crypto companies need a long time to accumulate enough reputation to reassure compliance officers at pension funds. However, this trust premium is a diminishing asset. For every year Kraken's clearinghouse operates smoothly and for every time Hyperliquid completes trillions of dollars in settlements without systemic incidents, the trust gap narrows by a fraction. The barrier of trust will gradually dissolve over time, with continuous records of incident-free operations. Five years ago, the crypto industry did not have these credible records; now it does.
Many in the crypto circle are excited because the HYPE token is rising, while traditional finance professionals are thrilled because established institutions have endorsed the protocols they favor. But now, Hyperliquid's competitors are no longer Binance or Coinbase. Its competitors are the CME clearinghouse, DTCC, and all global post-trade settlement systems. And in the most crucial aspect ------ perpetual contract settlement, its technology has already surpassed all competitors.
Sprecher has accepted a reality: technology has never been the moat. He has integrated the best infrastructure available today; even if the technology premium goes to zero, the value brought by regulatory qualifications is still sufficient to support a large business. I believe this judgment is correct. But he has also shown all other exchanges: the technology layer of exchanges can be replaced at any time.
-- Price
This content is provided for general informational purposes only and doesn't constitute financial, investment, legal, or tax advice. Any events, rewards, online promotions, or related information mentioned herein should not be considered a recommendation, solicitation, or invitation to purchase, sell, trade, or otherwise deal in any crypto assets. Crypto assets are highly volatile and may result in loss. The availability of WEEX services, products, and related events may vary by region. You are responsible for ensuring that your participation is in accordance with applicable local laws and regulations.
You may also like
Tria Lets AI Agents Trade Perpetuals With Restricted Keys
Hyperliquid Enters the US Market with Compliance Operations
Restraint and Expansion of Hyperliquid's Founder: No Financing, No Buying Houses, No Claiming to be an Exchange

Important News from Last Night and This Morning (November 2 - November 3)
Jon Leaves Hyperlane to Join Open Standard as Marketing Head
elizaOS Founder Reverse Engineers Hyperliquid's Closed Nodes with 46 Contributors
Comparison of Security Among Four Perpetual DEXs: Who Can Truly Enable User Self-Rescue?
Is Issuing Tokens Still Necessary for Crypto Projects Focused on Revenue?
What Kind of Tokens Can Survive Bull and Bear Markets?
The Token Issuance Game Has Been Ruined: Only Two Paths for Tokens to Survive in the Future
XPL Flash Crash Investigation: 16 Wallets Withdraw $2.0386 Million Margin, HLP Losses 55.6%
Follow the Money: $2.4 Billion in Investments, Major Round for Kalshi, and High Attention to AI — October 2026
Diversifying Your Crypto Portfolio: How Automated Indices Change the Game
ICE Deletes Collaboration Tweet with Trade.xyz, Retains Promotional Post
Stock Market Closure Leads to Liquidation in Tokenized Market
Diversification of Revenue Sources for Hyperliquid, Increase in USDC Reserve Yield Reported
Don Wilson Questions Six Core Issues of Hyperliquid
A Joke by Hyperliquid's Founder Becomes a Reality on Wall Street
Soros' Allies Join Forces with NYSE Parent Company to Bet Big on On-Chain Perpetual Market
[Column] The Message of ICE's Entry into the Perpetual Futures Market for Korea
US HYPE and ZEC Spot ETFs See Daily Net Inflow of $18.51 Million
Major Indexes Close Lower as Tech Comes Under Pressure | WEEX TradFi Daily(October 30, 2026)
All three major indexes closed lower on October 29, led down by technology and communication services; healthcare and defensive sectors were relatively resilient. Amazon and Intel came under pressure after hours. HYPE continued to rally toward its record high. TRX rose against the broader crypto-market decline. Investors will watch pre-market earnings from AbbVie, Exxon Mobil, Chevron and others on October 30.
WEEX Exclusive:Major Indexes Close Lower as Tech Comes Under Pressure | WEEX TradFi Daily(October 30, 2026)
Between Buy and Hold and Market Neutral: Understanding Semi-Neutral Strategies

Stanley Druckenmiller Invests in Trade.xyz and Posts First Tweet
Solana 2026: Ecosystem and Market Strategy Research
TradeXYZ Founder’s Remarks: I Have Been Ready to Walk This Path for Many Years
Hype Does Not Equal Moat: Solana's Wall Street Story Is Hard to Tell
Trade.xyz Partners with ICE to Create a Universal Exchange
Hyperliquid Removes 49.87 Million HYPE Tokens from Circulation
Tria Lets AI Agents Trade Perpetuals With Restricted Keys
Hyperliquid Enters the US Market with Compliance Operations
Restraint and Expansion of Hyperliquid's Founder: No Financing, No Buying Houses, No Claiming to be an Exchange
Important News from Last Night and This Morning (November 2 - November 3)
Jon Leaves Hyperlane to Join Open Standard as Marketing Head
elizaOS Founder Reverse Engineers Hyperliquid's Closed Nodes with 46 Contributors